

Insurance
15-20x Salary Term Cover on a Rs 15 Lakh CTC
Applying the 15-20x rule to a Rs 15 lakh CTC: why CTC overstates insurable income, the Rs 2.5-3 crore target, and how loans, riders and inflation adjust it.
In this guide
- The Quick Answer: How Much Cover for a ₹15 Lakh Salary
- How We Got These Numbers
- What It Costs at ₹15L CTC (30-Year-Old Non-Smoker, Male)
- Term Insurance Claim Settlement Ratio India (FY2024-25 IRDAI Data)
- Term + CI Combo: Rider vs. Standalone
- Your Action Plan: Run Quotes, Check Payouts, Decide on CI
- What a Rs 2.5 Crore Payout Actually Does for the Family
- CTC or In-Hand: Which Salary Do You Multiply?
You earn ₹15 lakh a year. There's a spouse at home, maybe kids, probably a home loan. So here's the real question: if something happened to you tomorrow, could your family keep going? Term insurance is built to answer that. But only if you buy the right amount. Most people get this wrong in one of two ways. They buy too little (₹50 lakh because "that's what my friend took") or too much (₹5 crore because an agent said "more is always better"). Both waste money. Let's work out what a ₹15 lakh salary actually needs.
If you earn ₹15 lakh, buy ₹2.25 to 3 crore of term cover from an insurer that pays above 98% of claims by amount. At 30, that's roughly ₹17,000 to ₹42,000 a year. Add critical illness cover if your budget allows. Run the live quotes this week. Don't wait for "someday" to protect the people who depend on you.
---
This is for educational purposes only. Talk to a qualified financial advisor for advice on your situation. Premiums and claim ratios change, so confirm current numbers before you buy. GST note: Individual term insurance is GST-exempt (0%) under Notification 16/2025-Central Tax (Rate), dated 17 Sep 2025 and effective 22 Sep 2025. Group term and group credit-life policies still carry 18% GST.
Key takeaways
- On a Rs 15 lakh CTC, take-home is closer to Rs 11-12 lakh — size the cover on income the family actually depends on.
- The 15-20x rule lands at Rs 2.5-3 crore for this salary; Rs 1 crore leaves a family under-insured within a decade.
- Add outstanding loans and children's education costs on top of the multiple.
- Inflation halves real cover value in roughly 12 years — review the sum insured every 5 years or on big life events.
- At 30-35, premiums for Rs 2.5-3 crore run roughly Rs 18,000-30,000 a year — cheap precisely because you are young and insurable.
The Quick Answer: How Much Cover for a ₹15 Lakh Salary
!undefined — explainer sketch, The Wealth Blog
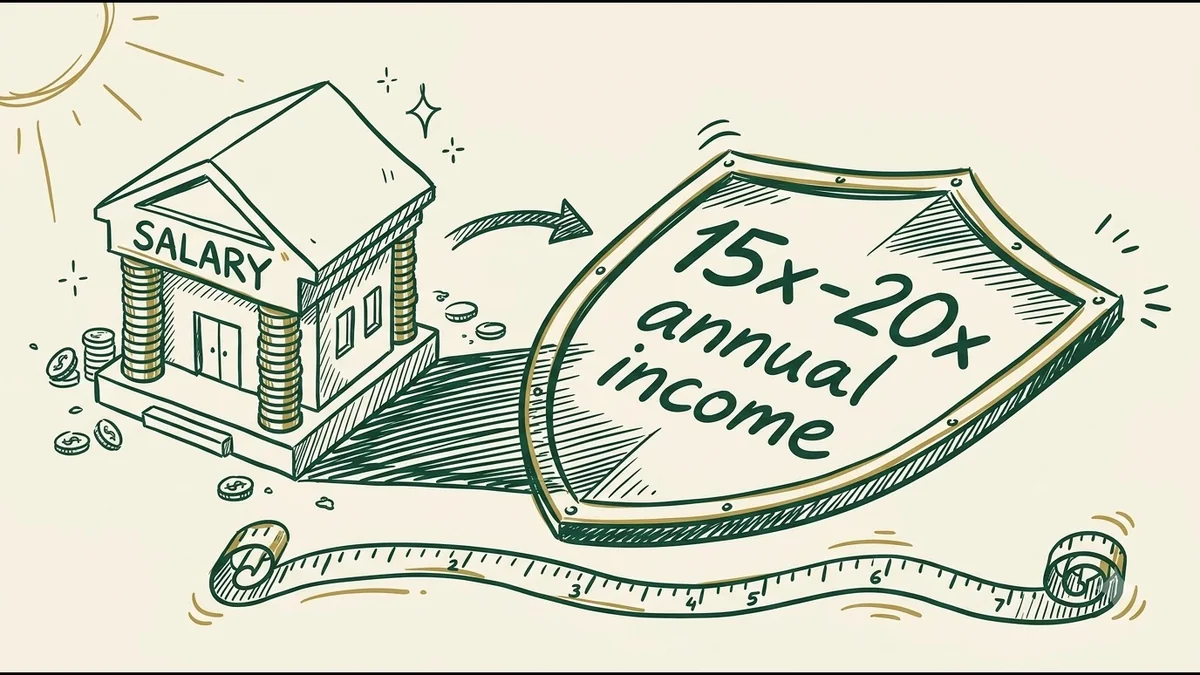
For a ₹15 lakh CTC, aim for ₹2.25 to 3 crore of cover.
- 15× your income = ₹2.25 crore
- 20× your income = ₹3 crore
- 25× = ₹3.75 crore, but insurers usually cap you at 20–25× and will ask for proof of income
Why that range? It replaces 15 to 20 years of your income. That's enough for your family to keep their lifestyle, pay off debts, and fund the big goals like the kids' education. You're not paying for cover you'll never use. Your move: Treat ₹2.25 crore as your floor. Stretch toward ₹3 crore if you have a home loan or young children.
How We Got These Numbers
4 of 4 rows
| Method | How it works | For ₹15L CTC |
|---|---|---|
| Income multiple (simplest) | Annual income × 15–25 | ₹2.25–3.75 crore |
| Human Life Value | Income × years left to work | ₹15L × 30 years = ₹4.5 crore, minus what you own and any loans |
| Expense replacement | Yearly expenses × years needed | Different for every family |
| Liabilities + goals | Loans + education + retirement fund | Built to your situation |
There are four ways to size up term cover:
For a salaried employee, the income multiple (15–20×) is the one that works. Insurers use it, financial planners use it, and it fits most budgets without strain. One thing to keep in mind: insurers cap cover at 20–25× your income. At ₹15 lakh, that's ₹3 to 3.75 crore at most. They'll want salary slips, Form 16, or your tax return when you apply. Don't pad the number. Your move: Use the 15–20× rule as your baseline. If a calculator spits out something wildly different, check the assumptions it made.
What It Costs at ₹15L CTC (30-Year-Old Non-Smoker, Male)
These are indicative rates pulled from insurer calculators in June 2026. Your actual quote will move with your age, health, BMI, city, and the policy term you pick.
GST Status: Individual Term Insurance Is Exempt (0%) Since 22 Sep 2025
Good news on tax: individual term insurance is GST-exempt (0%) from 22 September 2025 (56th GST Council meeting, Notification 16/2025-Central Tax Rate). What you see quoted is what you pay. No GST on top. The one exception: group term or group credit-life policies your employer arranges still carry 18% GST.
₹2 Crore Cover
| Plan | Annual Premium |
|---|---|
| ICICI Prudential iProtect Smart Plus | ₹19,283 |
| Axis Max Life Smart Term Plan Plus | ₹20,656 |
| HDFC Life Click2Protect Supreme Plus | ₹25,153 |
₹3 Crore Cover
4 of 4 rows
| Plan | Annual Premium |
|---|---|
| Bajaj Allianz Life eTouch II | ₹29,781 |
| Axis Max Life Smart Term Plan Plus | ₹33,240 |
| ICICI Prudential iProtect Smart Plus | ₹33,264 |
| HDFC Life Click2Protect Supreme Plus | ₹41,734 |
A few things that change your number:
- Women usually pay 15–20% less than men for the same age and plan.
- A critical illness rider adds cost on top of the base premium. It's usually moderate, but the exact amount varies, so check the calculator.
- Buying online often gets you 5–10% off the first year.
Your move: Pick the cover size from the step above, then run it through two or three insurer calculators to see your real number.
Term Insurance Claim Settlement Ratio India (FY2024-25 IRDAI Data)
This is the part people skip, and it matters most. Claim settlement ratio is just the share of claims an insurer actually pays. IRDAI's FY2024-25 data on individual death claims:
- Industry average: 98.32% settled by count, 97.18% by amount
- 97.1% paid within 30 days
Here's the catch with those two numbers. "By count" means how many claims got paid. "By amount" means how much money got paid. An insurer can settle 99% of claims by count but only 93% by amount. That means they're quietly rejecting the big claims. And the big claims are exactly the ones you're buying this policy for.
Top Insurers by Amount Settled (1,000+ claims)
5 of 5 rows
| Insurer | Paid by Amount | Paid by Count | Gap |
|---|---|---|---|
| PNB MetLife | 99.30% | 99.57% | 0.3 pp |
| Canara HSBC Life | 99.08% | 99.43% | 0.3 pp |
| Tata AIA | 98.57% | 99.43% | 0.9 pp |
| ICICI Prudential | 98.33% | 99.34% | 1.0 pp |
| HDFC Life | ~98.14% | ~99.68% | ~1.5 pp |
Red Flags: Wide Count-vs-Amount Gaps
| Insurer | Paid by Amount | Paid by Count | Gap | Average Denied Claim |
|---|---|---|---|---|
| Bajaj Allianz Life | 93.78% | 99.32% | 5.5 pp | ₹59.6 lakh |
| Shriram Life | 81.80% | 98.45% | 16.7 pp | ₹43.8 lakh |
The lesson: for a ₹2–3 crore cover, watch the amount-based number. A wide gap means they tend to reject the large claims. Your move: Only shortlist insurers that pay above 98% by amount. The names above (PNB MetLife, Canara HSBC, Tata AIA, ICICI Prudential, HDFC Life) clear that bar.
Term + CI Combo: Rider vs. Standalone
A plain term plan pays only if you die. A critical illness (CI) rider pays a lump sum if you're diagnosed with a covered illness, think cancer, heart attack, or stroke. Why bother? Because a serious illness can drain your savings long before a death claim ever comes into the picture. The rider pays you while you're still alive and treatment is happening. What it costs: a moderate add-on over the base premium. Not every insurer publishes exact CI rider prices, so run it on their calculator. The trade-off: some people prefer a standalone CI policy. It's usually more comprehensive and has its own separate sum assured. Others like the simplicity of a rider on the same plan. Compare the two before deciding. Your move: If there's a history of critical illness in your family, lean toward a standalone CI policy. Otherwise, a rider is a fine, simpler starting point.
Your Action Plan: Run Quotes, Check Payouts, Decide on CI
1. Run live quotes. Open the HDFC Life, ICICI Prudential, and Axis Max Life calculators. Enter: age 30, male, non-smoker, ₹2 crore or ₹3 crore, cover till age 65. Note the final premium (no GST to add for individual plans).
1. Check the amount-based payout rate. Shortlist insurers above 98% by amount (PNB MetLife, Canara HSBC, Tata AIA, ICICI Prudential, HDFC Life).
1. Decide on critical illness cover. Weigh a rider against a standalone policy. Family history tips you toward standalone.
1. Pull your documents together. Last 3 months of salary slips, Form 16, tax returns, bank statements. Insurers ask for these when you apply.
1. Apply online. Most insurers give 5–10% off the first year. And declare your smoking, drinking, and health history honestly. Hiding it can void your claim later.
1. Revisit after big life changes. Marriage, a child, a home loan, a salary jump. Each one changes how much cover you need.
What a Rs 2.5 Crore Payout Actually Does for the Family
Numbers on a policy document feel abstract. Here is the same number as a household budget. Illustration: the payout lands at Rs 2.5 crore and the family parks it at 6.5% in bank FDs (assumption: safe instruments, no equity risk in year one).
- Gross interest: about Rs 16 lakh a year, close to the Rs 11-12 lakh take-home the family lived on
- Principal untouched, so the corpus keeps earning through the school and college years
- At 6% inflation the same lifestyle costs roughly double in 12 years — redeploy into inflation-beating instruments once the dust settles, hence the five-year review
The point: Rs 2.5 crore is not rich-person money for a family that lost a Rs 15 lakh earner. It is one working lifetime of replacement, and it shrinks fast if it sits idle in a savings account.
CTC or In-Hand: Which Salary Do You Multiply?
| Base you multiply | The maths | Cover it suggests |
|---|---|---|
| In-hand (~Rs 11-12 lakh) | 15-20x | Rs 1.65-2.4 crore |
| Full CTC (Rs 15 lakh) | 15-20x | Rs 2.25-3 crore |
| CTC + loans and education goals | 20x + additions | Toward Rs 3-3.5 crore, subject to the insurer's income cap |
Applied to full CTC, the rule slightly over-insures: CTC overstates what the family depends on by 20-30%, since PF, gratuity provisions and employer insurance never reach the household budget. On a Rs 15 lakh CTC, in-hand is closer to Rs 11-12 lakh.
Here is the spread:
The spread between the first two rows is the cost of being wrong. Erring high costs a few thousand rupees of premium a year; erring low costs the family two decades of lifestyle. Your move: Treat Rs 2.25 crore as the floor, add the loan and education numbers, and let the total — not the multiple alone — set the final figure within the insurer's cap.
Frequently asked questions
How much term insurance for a Rs 15 lakh CTC?
Rs 2.5-3 crore — 15-20 times the take-home the family depends on, plus loans and education goals. Lock it in young: the same cover costs several times more at 45.
Should I calculate on CTC or take-home salary?
Take-home plus the benefits your family would lose (employer health cover, PF contributions). CTC overstates spendable income by 20-30%, so a CTC-based multiple over-insures slightly — err toward the higher number anyway.
Can I increase my term cover later?
Yes — most insurers offer step-up options on life events (marriage, child, home loan) with fresh underwriting, and buying a second policy later is common. Both cost more than buying adequate cover today.
About the author
Om Patel is an investor, blogger and entrepreneur. Every guide is educational, not personalised advice; rates and rules are cited to official sources and reviewed with a visible date.
Educational content, not personalised advice. Rates change — verify on the bank's site before opening an account. How we make money