

Debt Management
Rs 50K Credit Card Debt: Balance Transfer vs Loan
Escaping Rs 50,000 of credit card debt: how balance transfers, personal loans and EMI conversion really compare on cost, tenure and credit score damage.
In this guide
- Option 1: Balance Transfer — The 0% Window
- Option 2: Personal Loan — The 2-3 Year Fix
- Option 3: EMI Conversion — Same Card, Lower Rate
- Credit Score Impact
- The Decision Tree: Your Escape Plan
- Monthly Cash Flow Required
- Budget Repair Template (For >₹2L Debt)
- Action Steps: Do This Today If You Have Credit Card Debt
- Risks & Limitations
You have ₹50,000 on your credit card. The bill says "Minimum Due: ₹2,500." You pay it. Next month, the balance is ₹49,000. You pay ₹2,500 again. Balance: ₹48,000. At this rate, you'll be paying for 10+ years and shell out 3x the principal in interest. There's a way out. It takes 30 minutes. It saves you lakhs. Let me show you the decision tree — pick your debt amount, follow the path, take action today. Credit card debt in India is exploding:
- Outstanding: ₹2.92 lakh crore (Dec 2024) — up 15% in one year
- Gross NPAs: ₹6,742 crore — up 28.4% YoY
One number decides the escape route before any comparison shopping: run your own balance through the personal loan EMI calculator and see what a structured payoff costs per month.
- NPA ratio: 2.3% — rising fast
- 10.61 crore cards in circulation — 14% growth
- Delinquency (91-180 days): 7.6% — up 110 bps
- Average balance per card: ₹32,233 — up 11.5%
The pattern: Young millennials using full limit and defaulting without revolving — "direct to NPA" (Macquarie Capital). RBI's new NBFC/HFC FD rules (Jan 2025) make it worse: tighter FD withdrawals → NBFC liquidity crunch → higher credit card rates, stricter eligibility, fewer balance transfer offers.
### Your Three Escape Routes
| Option | Best For | Rate | Time to Clear | Credit Score Hit |
| --- | --- | --- | --- | --- |
| Balance Transfer | <₹50K, can clear in 3-4 months | 0% for 60-105 days | 3-4 months | -10 to -30 pts (new card inquiry) |
| Personal Loan | ₹50K-₹2L, need 2-3 years | 9.99-14% | 24-36 months | -10 to -25 pts (new loan inquiry) |
| EMI Conversion | Same card, convenience | 12-24% | 6-48 months | Minimal/None |
Credit card revolving at 36-48% is NEVER the answer. At 42%, ₹50K minimum payment takes 10+ years and costs ₹1.5L+ in interest.
---
Credit card debt at 36-48% is a financial emergency. Not "I'll handle it later." Every month you wait, the hole deepens. The math is simple:
- <₹50K + can clear in 3 months → Balance Transfer (0% window)
- ₹50K-₹2L → Personal Loan at 9.99-11% (Axis, Kotak, Tata)
- >₹2L → Personal Loan + budget repair + professional help if needed
Do this today: Open your banking app. Note the numbers. Pick the path. Apply. The 30 minutes you spend today saves you lakhs and years of stress. Your future self — the one sleeping peacefully without collection calls — is already thanking you.
---
Key takeaways
- Paying only the minimum due on Rs 50,000 keeps you in debt for years — monthly interest alone can cross Rs 10,000 at 42% annual rates.
- A balance transfer buys a 0% or low-interest window — useful only if you actually clear the balance inside it.
- A personal loan at 11-16% converts revolving debt into a fixed 2-3 year EMI plan with a hard end date.
- EMI conversion keeps everything on the card at a lower rate — simplest, but the card stays usable and temptation stays.
- All three routes can dip your credit score briefly; unpaid revolving debt damages it far more.
- The escape plan fails if the card keeps getting used — stop new spends before choosing the route.
Option 1: Balance Transfer — The 0% Window
Best Cards for 0% Balance Transfer (2024-25)
7 of 7 rows
| Bank/Card | 0% Period | Processing Fee | Max Transfer | Eligibility |
|---|---|---|---|---|
| Kotak Mahindra | 90 days | ₹349 per ₹10K + GST | 75% of limit | Card >6 months old |
| IDFC FIRST (CreditPro) | 105 days | 2% (min ₹499) + GST | Up to limit | Invite-only |
| SBI Card | 60 days | 2% or ₹199 (whichever higher) | 75% of limit | All SBI cards |
| Standard Chartered | 6 months @ 0.99%/mo | — | ₹5 Lakh | SC cardholders |
| HDFC Bank | No 0%; 1.1%/mo on EMI | 1% or ₹250 | 75% of limit | Pre-approved |
| ICICI Bank | No 0%; 1.25%/mo | 1-5% | Up to ₹3 Lakh | ICICI cardholders |
| Axis Bank | No 0%; 1%/mo | 1.5% or ₹250 | Up to ₹3 Lakh | Axis cardholders |
Best 0% Options: Kotak (90 days) and IDFC FIRST CreditPro (105 days). IDFC is invite-only with joining fee ₹749+GST (waived if BT in 15 days), annual fee ₹749 from year 2.
Total Cost: ₹50K Debt on Balance Transfer
| Option | 0% Period | Monthly to Clear | Fee | All-in Cost |
|---|---|---|---|---|
| Kotak 90-day 0% | 90 days | ₹16,667 | ₹1,745 | ₹51,745 |
| IDFC 105-day 0% | 105 days | ₹14,286 | ₹1,000 | ₹51,000 |
Winner for ₹50K (can clear in 3-4 months): Balance Transfer (IDFC/Kotak)
---
Option 2: Personal Loan — The 2-3 Year Fix
Rates by Lender Type (2024-25)
4 of 4 rows
| Lender Type | Rate Range | ₹50K | ₹1L | ₹2L | ₹5L |
|---|---|---|---|---|---|
| Public Sector Banks (SBI, PNB, BoB) | 10.5-14% | 10.5-12% | 10.5-12% | 10.5-12% | 10.5-12% |
| Private Banks (HDFC, ICICI, Axis) | 10.5-16% | 10.5-13% | 10.5-13% | 10.5-13% | 10.5-13% |
| NBFCsFCsFCs (Bajaj, Tata Capital, IDFC First) | 11-24% | 12-16% | 11-15% | 11-15% | 11-14% |
| Fintech (KreditBee, MoneyTap, Navi) | 15-36% | 18-24% | 16-22% | 15-20% | 14-18% |
Specific Bank Rates (2024-25)
5 of 5 rows
| Bank | Starting Rate | ₹50K EMI (3 yr) | ₹1L EMI (3 yr) | ₹2L EMI (3 yr) | ₹5L EMI (3 yr) |
|---|---|---|---|---|---|
| Axis Bank | 9.99% | ₹1,611 | ₹3,222 | ₹6,444 | ₹16,110 |
| Kotak | 10.99% | ₹1,636 | ₹3,271 | ₹6,543 | ₹16,357 |
| Tata Capital | 10.99% | ₹1,636 | ₹3,271 | ₹6,543 | ₹16,357 |
| SBI | ~11-12% | ~₹1,645 | ~₹3,290 | ~₹6,580 | ~₹16,450 |
| Bajaj Finserv | 10% | ₹1,613 | ₹3,227 | ₹6,453 | ₹16,133 |
Rates depend on CIBIL (750+ for best), income, employer, existing obligations. Processing fees 1-3%, prepayment 0-5%.
Total Cost: ₹50K and ₹2L Debt on Personal Loan
₹50K Debt
| Option | Rate | Tenure | Monthly EMI | Total Interest | All-in Cost |
|---|---|---|---|---|---|
| Axis 9.99% | 9.99% | 24 mo | ₹2,307 | ₹5,368 | ₹55,868 |
| Kotak 10.99% | 10.99% | 24 mo | ₹2,330 | ₹5,920 | ₹56,420 |
₹2 Lakh Debt
| Option | Rate | Tenure | Monthly EMI | Total Interest | All-in Cost |
|---|---|---|---|---|---|
| Axis 9.99% | 9.99% | 36 mo | ₹6,452 | ₹32,272 | ₹2,33,272 |
| Tata 10.99% | 10.99% | 36 mo | ₹6,547 | ₹35,692 | ₹2,36,692 |
Winner for ₹50K (need 2 years): Personal Loan (Axis 9.99%) Winner for ₹2L: Personal Loan (Axis 9.99% for 36 months)
---
≈ ₹5.00 L
- Monthly EMI
- ₹16,607
- Total interest
- ₹97,858
- Total payment
- ₹5,97,858
- Principal ₹5,00,000(84%)
- Interest ₹97,858(16%)
Year-by-year schedule
| Year | Principal paid | Interest paid | Balance |
|---|---|---|---|
| 1 | ₹1,47,208 | ₹52,078 | ₹3,52,792 |
| 2 | ₹1,65,877 | ₹33,408 | ₹1,86,915 |
| 3 | ₹1,86,915 | ₹12,371 | ₹0 |
Option 3: EMI Conversion — Same Card, Lower Rate
EMI Conversion Rates on Major Cards
9 of 9 rows
| Bank | Monthly Rate | Annual APR (IRR) | Processing Fee | Pre-closure | Tenure | Min Txn |
|---|---|---|---|---|---|---|
| HDFC (SmartEMI) | 0.99% starting | 11.88-24.96% | — | 3% of principal | 6-48 mo | ₹2,500 |
| HDFC (EasyEMI) | — | 11.56-21% | ₹99-699+GST | — | 3-48 mo | — |
| SBI (Flexipay) | — | 16-22% | 2% (₹199-1,000) | 3% of principal | 3-24 mo | ₹2,500 |
| ICICI (Instant EMI) | — | 12-20% | 2.99% (max ₹299+GST) | — | 3-24 mo | — |
| Axis Bank | 1.5% | 18% | 1.5% or ₹150 | 3% of principal | 6-24 mo | ₹2,500 |
| Kotak | 1.16-1.67% | 13.92-20.04% | Nil-₹35/₹1000 | Nil | 3-48 mo | ₹2,500 |
| Amex (Plan It) | 1.17% | 14.04% | 2% | Nil | 3-24 mo | ₹5,000 |
| YES Bank | 1-1.25% | 12-15% | Nil | 2% of principal | 3-24 mo | ₹2,500 |
| IDFC First | 2.99% | ~42.3% | — | — | — | — |
Key Insight: EMI conversion on same card = 12-24% p.a. vs credit card revolving at 36-48% p.a. — significant savings but still expensive vs personal loan (10-14%).
---
Credit Score Impact
6 of 6 rows
| Action | CIBIL Impact | Duration | Notes |
|---|---|---|---|
| Balance Transfer (new card) | -10 to -30 pts | 6-12 months | Hard inquiry + new account lowers avg age |
| Personal Loan (new) | -10 to -25 pts | 6-12 months | Hard inquiry; improves mix if no prior installment loan |
| EMI Conversion (same card) | Minimal/None | — | No new inquiry; utilization may increase temporarily |
| Closing Old Card (post-BT) | -15 to -50 pts | 12-24 months | Reduces total limit → higher utilization % |
| Default / 90+ DPD | -100 to -200 pts | 7 years | Severe; reported as NPA |
| Settlement | -75 to -150 pts | 7 years | "Settled" status worse than "Closed" |
Critical: Don't close your old card after balance transfer! It reduces total limit → utilization spikes → score drops. Keep it open, cut it up if needed.
---
The Decision Tree: Your Escape Plan
!undefined — explainer sketch, The Wealth Blog
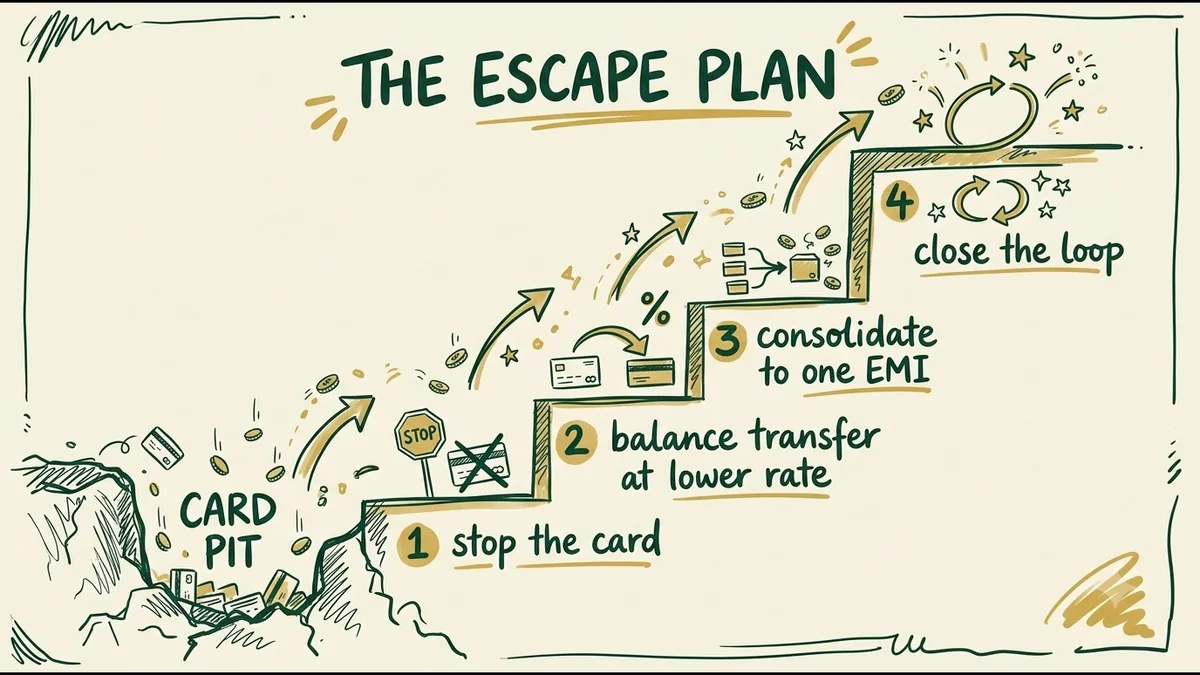
START: Total Credit Card Debt = ₹X │ ├─ X < ₹50,000 │ └─ Can you clear in 3-4 months? │ ├─ YES → **Balance Transfer** (Kotak 90d 0% or IDFC 105d 0%) │ │ • Transfer fee: ~2-3.5% │ │ • Must have eligible card >6 months old │ │ • Pay aggressively during 0% window │ └─ NO → **Personal Loan** (Axis 9.99% / Kotak 10.99%) │ • 24-36 month tenure │ • Lower EMI than card revolving │ ├─ ₹50,000 ≤ X < ₹2,00,000 │ └─ **Personal Loan** (Best rates 9.99-11%) │ • Compare 5+ lenders (rate diff 2-4% common) │ • Choose shortest affordable tenure │ • Avoid fintech/NBFC >15% unless desperate │ ├─ ₹2,00,000 ≤ X < ₹5,00,000 │ └─ **Personal Loan + Budget Repair** │ • Consolidate all cards into 1 PL │ • Cut expenses to free ₹10-15K/mo extra │ • Consider loan against securities/FD if lower rate │ └─ X ≥ ₹5,00,000 └─ **Debt Consolidation + Professional Help** • Multiple PLs or Loan Against Property • Credit counseling (Freed, etc.) • Avoid settlement (CIBIL damage 7 years)
---
Monthly Cash Flow Required
5 of 5 rows
| Debt Amount | Option | Tenure | Monthly Outflow | % of ₹50K Salary | % of ₹1L Salary |
|---|---|---|---|---|---|
| ₹50,000 | BT (90d 0%) | 3 mo | ₹16,667 | 33% | 17% |
| ₹50,000 | PL (9.99%, 24m) | 24 mo | ₹2,307 | 4.6% | 2.3% |
| ₹1,00,000 | PL (9.99%, 24m) | 24 mo | ₹4,614 | 9.2% | 4.6% |
| ₹2,00,000 | PL (9.99%, 36m) | 36 mo | ₹6,452 | 12.9% | 6.5% |
| ₹5,00,000 | PL (10.99%, 48m) | 48 mo | ₹12,920 | 25.8% | 12.9% |
Rule of Thumb: Total EMI ≤ 40% of net salary. If exceeding → need budget repair + longer tenure.
---
Budget Repair Template (For >₹2L Debt)
Step 1: List Every Expense
Income: ₹______/month Fixed: Rent ₹____, EMIs ₹____, Insurance ₹____, SIPs ₹____ Variable: Food ₹____, Transport ₹____, Shopping ₹____, Entertainment ₹____
Step 2: The 50/30/20 Reality Check
- Needs (50%): Rent, food, utilities, minimum debt payments
- Wants (30%): Dining out, subscriptions, shopping, travel
- Savings/Debt (20%): Extra debt payment, emergency fund, investments
Step 3: Find ₹10-15K/Month Extra
7 of 7 rows
| Quick Wins | Potential Savings |
|---|---|
| Pause SIPs temporarily | ₹5-15K |
| Switch to cheaper phone plan | ₹500-1K |
| Cut OTT subscriptions | ₹500-2K |
| Cook at home vs ordering | ₹3-8K |
| Public transport vs cab | ₹2-5K |
| Sell unused items (OLX) | One-time ₹10-50K |
| Freelance/overtime | ₹5-20K |
Step 4: Snowball vs Avalanche
- Snowball: Pay smallest balance first (psychological wins)
- Avalanche: Pay highest rate first (mathematically optimal)
- For credit cards: Avalanche wins — rates are all 36-48%, so pay highest balance first
---
Action Steps: Do This Today If You Have Credit Card Debt
Immediate (Next 30 Minutes)
1. Check total debt — log into all cards, note exact outstanding, interest rate, minimum due 2. Check CIBIL score — free on Paisabazaar, BankBazaar, or CIBIL directly 3. Pick your path using the decision tree above 4. Apply — balance transfer (online, instant) or personal loan (compare 5+ lenders)
This Week
1. If Balance Transfer: Transfer full amount. Set calendar reminder for day 80/100 to clear or re-evaluate. 2. If Personal Loan: Get sanction letter. Pay off ALL cards. Keep one card open (cut it up). 3. If EMI Conversion: Convert on lowest-rate card. Don't use that card for new spends. 4. Set up auto-pay for new EMI — never miss a payment.
This Month
1. Build ₹10K emergency fund — so you never need the card again 2. Track every rupee — use a spreadsheet or app (Walnut, Money Manager, etc.) 3. Review subscriptions — cancel unused ones 4. Tell family/partner — accountability works
Quick Checklist
☐ Total debt calculated across all cards ☐ CIBIL score checked ☐ Decision tree path chosen ☐ Application submitted (BT / PL / EMI) ☐ Old cards paid off and kept open (cut up) ☐ Auto-pay set up for new EMI ☐ Emergency fund started (target ₹10K) ☐ Monthly budget reviewed for ₹10K+ savings
---
Risks & Limitations
- Balance transfer only works if you CLEAR it in the 0% window — otherwise revert rate 42% kills you; processing fee 2-3.5% upfront
- IDFC CreditPro 105 days is invite-only — joining fee ₹749+GST, annual fee ₹749 from yr 2
- Personal loan adds hard inquiry — score drops 10-25 pts for 6-12 months
- EMI conversion blocks credit limit — pre-closure penalties 2-3%
- Fintech instant loans 15-36% — often worse than credit card EMI; debt trap risk
- Settlement destroys CIBIL for 7 years — "Settled" status blocks all formal credit; better to take PL and repay
- RBI FD rules affect card funding — NBFCs fund credit card receivables via FDs; tighter FD rules → higher cost of funds → higher card rates
- Multiple balance transfers = serial BT flag — each BT = hard inquiry + fee; banks flag serial BTers; CIBIL damage accumulates
- This is educational, not financial advice — consult a credit counselor or financial advisor for your specific situation
Frequently asked questions
Is a balance transfer better than a personal loan for credit card debt?
A balance transfer is cheaper if you can clear the debt inside the low-interest window (usually 60-90 days). If you need 2-3 years, a personal loan at a fixed EMI is the more honest structure — the transfer window ends and the rate jumps.
Does converting credit card dues to EMI hurt my credit score?
The conversion itself is neutral; it restructures what you already owe. The score takes a hit if the EMI is missed or if you keep spending on the card while converting.
How fast can I escape Rs 50,000 of credit card debt?
With a fixed payment of about Rs 4,700 a month at a 13% personal-loan rate, roughly 12 months. Paying only the minimum due instead can stretch the same debt past five years.
About the author
Om Patel is an investor, blogger and entrepreneur. Every guide is educational, not personalised advice; rates and rules are cited to official sources and reviewed with a visible date.
Educational content, not personalised advice. Rates change — verify on the bank's site before opening an account. How we make money