

Credit Cards
Credit Card Stack 2027: The Zero-Fee Math, Line by Line
A zero-fee two-card stack returns ₹8,784 a year in points and cash — up to ₹39,396 with every perk used. Every rate, assumption and source is shown.
In this guide
- The two thresholds that decide your return — on the food stack
- The problem with the usual stack advice
- Stack 1: Amazon Pay ICICI + IndusInd Tiger (the ₹0-fee pair)
- Stack 2: Amazon Pay ICICI + HSBC Live+ (the food-heavy pair)
- Does this beat the ₹12,500 card?
- The 3-card question
- What breaks when the bank trims the benefit
- What each application costs your credit score
- Your action step today
- Sources
Rates as on 1 October 2026; HSBC Live+ structure effective from 26 July 2026; SBI Cashback changes effective from 1 April 2026. Last reviewed 1 October 2026.
- Every rupee on this page is recomputed from the card’s own published rate table, and each one shows its earn rate, its monthly assumption and its annual total as three separate lines.
- Every rate, cap and fee carries the date of the bank document it came from — and where a date could not be confirmed, the page says so instead of guessing.
- You can redo every sum on your own calculator. That is the point: a headline number is not the sum of its parts.
Most “best credit card” lists in India push you toward a premium card with a big annual fee. They show you the rewards. They skip the arithmetic.
So let’s do the arithmetic ourselves. Every rupee below is recomputed from the card’s own published rate table, and each one shows the earn rate, the monthly assumption and the annual total as three separate lines so you can redo the sum on your own calculator.
One note on scope before we start. Every example here runs on ₹30,000 a month of card spend. If you spend more or less, scale your own number against the thresholds as you read — the flat spots are named, and there are only two of them that matter.
---
Four numbers in this article did not survive checking, including two that were mine. The common thread wasn’t carelessness in reading the terms — it was skipping the multiplication after reading them. A number is not verified until it survives the condition attached to it. That’s the whole reason each figure here shows its rate, its monthly assumption and its annual total separately. These programs change quietly, and the person writing the list is not doing your maths for you.
---
Key takeaways
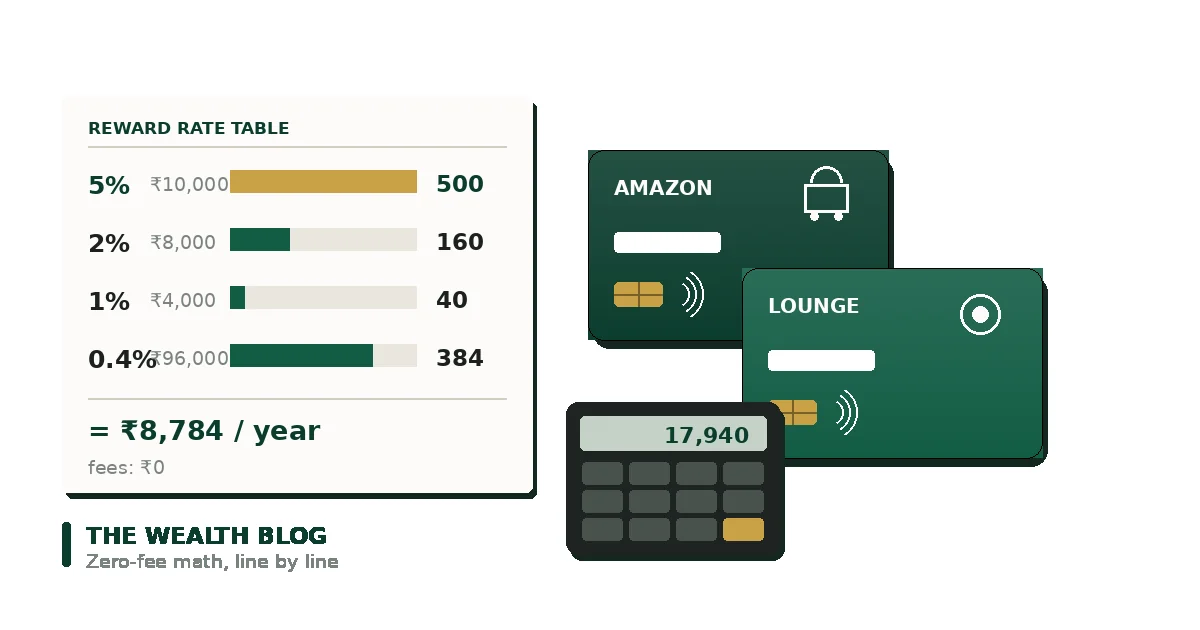
- At Rs 30,000 a month of card spend, the zero-fee Amazon Pay ICICI + IndusInd Tiger pair returns Rs 8,784 a year in points and cash — up to Rs 39,396 if you use every lounge visit and golf game.
- The food-heavy alternative (Amazon Pay ICICI + HSBC Live+) returns Rs 17,940 a year, rising to Rs 18,940 if you clear the fuel threshold.
- Every rate here is recomputed from the card's own published rate table with sources shown — the SBI Cashback cap cut to Rs 2,000 per cycle from 1 April 2026 shows why the maths needs rechecking yearly.
- A premium card only beats the stack if you already clear its fee-waiver thresholds — at Rs 3.6 lakh of annual spend, the Rs 12,500 fee is 3.47% of spend.
- Two cards cover most people; every extra application is a hard enquiry, so space them 6-12 months apart.
- Carried interest destroys the maths: 3.5-3.8% a month is roughly 42-45.6% a year, and credit-card interest is not capped by the RBI.
The two thresholds that decide your return — on the food stack
Both thresholds in this section belong to HSBC Live+, the card in Stack 2 below. They are not general rules for credit cards, and neither card in Stack 1 has either of them. Read them as the HSBC test.
If you spend more or less than ₹30,000, these are the two numbers that move your result, and both are flat spots rather than slopes.
The 10% bucket goes flat past ₹12,000 a month of qualifying spend. The cap is ₹1,200, and 10% of ₹12,000 is ₹1,200. Spend ₹13,000 in that bucket and you earn the same as someone spending ₹12,000. Spend ₹30,000 there and you still get ₹1,200. Past that point, extra grocery or dining spend earns you nothing on this card — so route it elsewhere, or don’t worry about optimising it.
The fuel perk switches on at roughly ₹3,334 a month in contactless fuel, sustained every quarter (₹10,000 ÷ 3). This is a different kind of benefit entirely, and it’s worth understanding before you assume it. A threshold perk pays a fixed amount once you cross a spending level, rather than paying a percentage of what you spend. The fuel benefit behaves nothing like the 10% bucket: ₹2,000 a month — a perfectly ordinary amount — earns you nothing, because it’s ₹6,000 a quarter against a ₹10,000 threshold. Cross about ₹3,334 a month and ₹250 a quarter switches on. Spend ₹5,000 a month in fuel and you get the same ₹250 as someone at ₹3,334. Check your own quarterly fuel number before you count this benefit.
---
The problem with the usual stack advice
A credit card stack means using two or three cards for the same life, each one assigned to a category where it pays best. Amazon on one card. Food on another. Everything else on a third.
The idea is sound. The marketing around it usually isn’t. Three things go wrong:
1. Nobody counts the credit score cost. Every application is a hard enquiry — a formal check of your credit report that the bank logs and that stays visible on your report for years.
1. Nobody shows the earn rate. “5% back” means nothing without knowing what spend it applies to.
1. Nobody says what happens when the bank trims the benefit. These programs change. Often.
Let’s fix all three, one stack at a time.
---
Stack 1: Amazon Pay ICICI + IndusInd Tiger (the ₹0-fee pair)
Card 1 — Amazon Pay ICICI Credit Card
Terms last updated on 13 January 2026 (ICICI Bank MITC — the bank’s master terms and conditions, the one document that states every rate — p.1). Joining fee: NIL. Annual fee: NIL (ICICI product page, Fees & Charges).
The 5% question — why two bank documents look like they disagree
One thing trips people up on this card, so let’s clear it first: Amazon shopping and Amazon Pay travel are two separate 5% routes, described in two separate places. The MITC says:
“For Card Members having Prime Membership, earn rate of the Reward Points will be 5% of the transaction amount for all the transactions done at www.amazon.in (Excluding Gold Coins and travel bookings for flights & hotels via Amazon Pay)”
And ICICI’s own newsroom of 11 September 2025 separately lists, under its heading “More Value on Travel”:
“5% unlimited cashback on travel bookings (flights and hotels) via Amazon Pay for Prime members”
The exclusion clause carves travel out of the Amazon shopping bucket so it doesn’t get counted there twice — it does not remove the travel benefit. Nothing in this stack assumes travel spend, so ₹8,400 stands either way.
The full earn rates, from the MITC:
- 5% on transactions at www.amazon.in, if you hold Amazon Prime — excluding Gold Coins and travel bookings for flights & hotels via Amazon Pay
- 3% on transactions at www.amazon.in, if you don’t hold Prime — same exclusions
- 2% on digitally fulfilled categories — logging in and paying with Amazon Pay, and physical gift cards
- 1% on all other purchases at www.amazon.in
Per the same MITC, all Reward Points are credited as Amazon Pay balance within 2 working days of your billing cycle closing, in the form of Amazon Gift Cards.
The math
7 of 7 rows
| Category | Monthly spend | Earn rate | Monthly reward |
|---|---|---|---|
| Amazon.in general (you have Prime) | ₹10,000 | 5% | ₹500 |
| Amazon Pay digital / gift cards | ₹8,000 | 2% | ₹160 |
| Other amazon.in purchases | ₹4,000 | 1% | ₹40 |
| Amazon-routed subtotal | ₹22,000 | — | ₹700 |
| Offline general spend | ₹6,000 | routed to Card 2 | — |
| Dining + delivery | ₹2,000 | routed to Card 2 | — |
| Total card spend | ₹30,000 |
Assume you spend ₹30,000 a month on your card, split this way:
Annual total on this card: ₹700 × 12 = ₹8,400.
One thing to understand before you get excited: this reward lands in your Amazon Pay balance as Amazon Gift Cards. It is not cash. It is Amazon money. Use it for something you were buying on Amazon anyway, and it is genuinely 5% off. Try to convert it to bank cash and you will be disappointed.
Also note what no longer earns, per the same MITC: with effect from 11 October 2025, education and international transactions earn nothing, and utility transactions outside Amazon earn nothing. Rent has earned nothing since 18 June 2024. Fuel, gold, silver, precious metals and tax payments never earned. EMI transactions earn nothing, and if you later convert a transaction to EMI, the points are clawed back.
Card 2 — IndusInd Bank Tiger Credit Card
5 of 5 rows
| Slab | Spend | Reward value | Effective rate |
|---|---|---|---|
| Slab 1 | ₹1,00,000 | ₹400 | 0.40% |
| Slab 2 | ₹1,50,000 | ₹1,200 | 0.80% |
| Slab 3 | ₹2,50,000 | ₹4,000 | 1.60% |
| Slab 4 | ₹1,00,000 | ₹2,400 | 2.40% |
| Total | ₹6,00,000 | ₹8,000 | 1.33% cumulative |
Co-branded with Tiger Fintech Private Limited, a Bajaj Capital Group company, under a revenue-sharing arrangement with IndusInd Bank — per IndusInd’s own product page. Worth knowing, because it tells you who is being paid when you use the card.
Terms per the IndusInd Bank consolidated MITC, dated 31 August 2026. Joining fee: NIL. Annual fee: NIL. (The reward slab table and perk values below come from IndusInd’s product page, not from that MITC — flagging the source difference, since the two are not the same document.)
The reward side is where people get confused, so let’s be precise. IndusInd publishes a “Magnificent Rewards” program worth up to 6 accelerated reward points per ₹100. One reward point is worth ₹0.40 when you redeem it against your card outstanding. And with effect from 1 September 2024, reward points allowed for cash redemption are capped at 5,000 per calendar month.
The bank’s own published value table breaks down what ₹6,00,000 of annual spend earns you:
Those are marginal rates. Each slab’s rate applies only to the spend inside it. Read that table carefully and you will see something important: on modest spend, this card is a weak rewards earner. It is a lounge card.
In our stack, only ₹8,000 a month (₹96,000 a year) routes here — your offline and dining spend. That sits entirely inside Slab 1.
- Earn rate applied: 0.40%
- Monthly assumption: ₹8,000 routed spend
- Annual reward value: ₹96,000 × 0.40% = ₹384
So the honest picture on this card is: ₹384 of points, plus perks you either use or don’t.
What the Tiger actually gives you
5 of 5 rows
| Benefit | Bank’s stated annual value |
|---|---|
| Golf — 4 complimentary games or lessons at ₹4,000 each | ₹16,000 |
| Domestic lounges — 8 visits per year at $14 | ₹9,184 |
| International lounges — 2 visits per year at $27 | ₹4,428 |
| BookMyShow — assured 2 tickets of ₹500 per year | ₹1,000 |
| Total value to customer | ₹38,612 |
From the bank’s published value table, at ₹6L annual spend:
Those dollar figures use an ₹82/USD rate, per the bank’s note.
One clarification worth having: these golf, lounge and cinema benefits are fixed annual entitlements, not slab-gated. They do not scale with your spend. At our ₹96,000 routed spend you still get the same eight lounge visits and four golf games as someone spending ₹6 lakh. The rewards points scale; the perks do not.
Read the ₹38,612 line twice. That is what you get if you use every single benefit. Not one rupee of it is automatic. If you skip the airport in a given year, the international lounge value is not banked — it is gone. If you don’t play golf, the ₹16,000 evaporates.
Stack 1, total
7 of 7 rows
| Line | Amount |
|---|---|
| Amazon Pay ICICI rewards | ₹8,400/yr |
| IndusInd Tiger points (at 0.40%) | ₹384/yr |
| Cash-like subtotal | ₹8,784/yr |
| Tiger lounges (if used) | ₹13,612/yr |
| Tiger golf + BookMyShow (if used) | ₹17,000/yr |
| Maximum realistic value, everything used | ₹39,396/yr |
| Annual fees | ₹0 |
Footnote on the figures I was handed. The dossier put this card at ₹8,500 and the stack at ₹12,100. Its own components come to ₹700 a month, or ₹8,400 a year, and the lounge line was deflated by roughly 80% against IndusInd’s own table. Neither figure survives. The check is the simple one: a headline number is not the sum of its parts.
If your actual life involves airports and golf, this stack is excellent. If it doesn’t, you are holding a lounge card for a lifestyle you don’t have.
---
Stack 2: Amazon Pay ICICI + HSBC Live+ (the food-heavy pair)
For a household where eating out and ordering in is a real monthly line, not an occasional one.
Card 2 — HSBC Live+ Credit Card
Per the HSBC product page, as on 1 October 2026, with the revised structure effective from 26 July 2026:
- 10% accelerated cashback, capped at ₹1,200 a month, on dining, food delivery, groceries, shopping and utility spends
- 1.5% unlimited cashback on most other spends — but not on international spends, with effect from 26 July 2026
- Fuel: ₹250 cashback per quarter on contactless fuel spends of ₹10,000 or more per quarter, effective from 26 July 2026
- Joining fee: ₹999 (₹1,178.82 with 18% GST)
- Annual fee: ₹999, waived if you spend more than ₹2,00,000 per year
- 2 domestic and 1 international airport lounge visit per year
- Foreign exchange markup: 1.99% on international transactions (HSBC product page, as on 1 October 2026)
Two corrections to the research I was handed, both material. The briefing material put the monthly cap at ₹1,000 and described the 10% as excluding food. The live page says ₹1,200, and the 10% bucket includes dining and food delivery — along with groceries, shopping and utilities. The briefing understated this card, and understated it by ₹200 a month on the cap alone. Both changes date from 26 July 2026, which is what supersedes the older terms.
The math at ₹30,000 total monthly spend
8 of 8 rows
| Category | Monthly spend | Rate | Cashback |
|---|---|---|---|
| Dining | ₹4,000 | 10% | ₹400 |
| Food delivery | ₹2,000 | 10% | ₹200 |
| Groceries | ₹5,000 | 10% | ₹500 |
| Utilities | ₹2,000 | 10% | ₹200 |
| 10% bucket subtotal | ₹13,000 | raw ₹1,300 | capped at ₹1,200/mo |
| All other spend, excluding fuel | ₹11,000 | 1.5% | ₹165 |
| Fuel | ₹2,000 | ₹250/quarter on ₹10,000+ per quarter | ₹0 |
| Amazon spend → routed to Amazon Pay ICICI | ₹4,000 | see below | — |
HSBC Live+, line by line:
- 10% bucket: ₹13,000/mo at 10% = ₹1,300 raw → capped at ₹1,200/mo = ₹14,400/yr
- 1.5% bucket: ₹11,000/mo at 1.5% = ₹165/mo = ₹1,980/yr
- Fuel benefit: ₹0 — ₹2,000/mo is ₹6,000/quarter against a ₹10,000/quarter threshold, so it does not qualify
- Annual: ₹14,400 + ₹1,980 + ₹0 = ₹16,380
Applying the two thresholds
The thresholds that decide this card’s return were set out at the top of this article — the ₹12,000 flat spot on the 10% bucket, and the ₹10,000-per-quarter fuel switch-on. Both apply to this stack, and on the ₹30,000 assumption above the 10% bucket is already past its cap and the fuel spend does not qualify.
The Amazon line in this stack
4 of 4 rows
| Category | Monthly spend | Earn rate | Monthly reward |
|---|---|---|---|
| Amazon.in general (Prime) | ₹2,000 | 5% | ₹100 |
| Amazon Pay digital / gift cards | ₹1,000 | 2% | ₹20 |
| Other amazon.in | ₹1,000 | 1% | ₹10 |
| Amazon-routed total | ₹4,000 | 3.25% blended | ₹130 |
An earlier version of this article put the Amazon Pay ICICI contribution here at ₹4,560 a year. That would have been a 9.5% return — roughly double what the card can pay on any spend. The card’s ceiling is 5%, so no combination of its rates produces it. The teaching is the whole point: check what rate the number implies before you check how you got it.
Here is the split:
Annual: ₹130 × 12 = ₹1,560. That is a 3.25% blended rate, under the 5% ceiling, because only part of the mix earns the top rate.
Stack 2, total
4 of 4 rows
| Line | Amount |
|---|---|
| HSBC Live+ cashback | ₹16,380/yr |
| Amazon Pay ICICI rewards (₹4,000/mo Amazon mix at 3.25% blended) | ₹1,560/yr |
| Total | ₹17,940/yr |
| Annual fee (waived above ₹2L spend) | ₹0 |
One caveat on that total: it assumes the ₹2,000-a-month fuel spend above, which misses the fuel threshold. If you clear about ₹3,334 a month in contactless fuel, the fuel benefit adds ₹1,000 and the stack returns ₹18,940.
---
Does this beat the ₹12,500 card?
HDFC Bank’s published fee schedule for the Infinia Metal Edition (Version 2.5, dated Mar-2025, updated on 6th March ’25) lists Infinia (Metal Edition): ₹12,500 plus applicable taxes, waived at ₹10 lakh per annum. With 18% GST the real payable is ₹14,750.
There are two thresholds in play and you should know both: the published ₹10 lakh waiver on the fee schedule, and a communicated requirement of ₹18 lakh of annual card spend, or a ₹50 lakh relationship value, per reporting on a bank communication sent to Infinia cardholders. That communication carries no announced effective date, which is why none is stated here.
At ₹3,60,000 of annual spend, the Infinia Metal fee is 3.47% of your spend — nowhere near either threshold. So a ₹0-fee stack returning ₹17,940/yr beats the ₹12,500 (₹14,750 with GST) fee for anyone spending below ₹18 lakh a year against the communicated threshold, and well below that against the published one.
But be honest about the trade. Infinia is not a bad card. It is a bad card for your spend level. It is built for someone clearing ₹18 lakh a year who values airport access and travel redemptions. If that is you, the threshold does its job and this comparison does not apply.
One more check on the premium-card narrative. HDFC’s Regalia Gold product communication confirms: *3 domestic lounge visits per calendar quarter on spends of ₹60,000 or more in the preceding calendar quarter, applicable from the calendar quarter starting 1st July 2026. To use lounges in Jul–Sep 2026, you must spend ₹60,000 in Apr–Jun 2026. It is a preceding*-quarter rule, and a missed quarter costs you the following one.
---
The 3-card question
Don’t add a third card unless all three are true:
1. The third card has a category the first two genuinely don’t cover — usually international travel or forex. Not “it’s on offer.”
1. You can clear its fee-waiver threshold without moving spend you already earn on elsewhere.
1. You will still pay every bill in full. See below for what carrying a balance really costs.
There is a fourth, unwritten condition: can you remember the routing rules? Two cards, you will. Three, some people won’t within six months. And the discipline required by a stack is the single biggest reason real returns fall short of the math.
What carrying a balance really costs
Per the ICICI product page, Fees & Charges, as on 1 October 2026, if only the minimum amount due is paid, you pay 3.75% interest per month. ICICI’s own communication states the rate varies dynamically from 3.5% to 3.8% per month depending on the customer’s behaviour and performance — roughly 42% to 45.6% a year nominal, and closer to 56% compounded monthly.
This is a board-approved policy rate disclosed in the card’s terms, not a regulated lending rate — credit-card interest sits outside the RBI’s interest-rate-on-advances framework and outside any RBI cap. Either end of that band destroys every reward on this page. A single ₹10,000 balance carried for three months at 3.5% costs about ₹1,050, which erases the better part of a year of optimisation. If a balance is the problem rather than your card choice, that is a different problem — start with the credit card debt escape plan.
If bills are the problem, not Amazon or food
The stacks above assume your bills and utilities are on autopay or UPI. On Amazon Pay ICICI, utility transactions outside Amazon stopped earning with effect from 11 October 2025. Don’t route bill payments to a rewards card expecting a return — there isn’t one. On HSBC Live+, utility spends sit inside the 10% bucket, but that bucket is capped, so fill the cap with your highest-frequency categories first.
---
What breaks when the bank trims the benefit
On the SBI Cashback card — per SBI Card’s own customer-notices page, website notice dated 27 February 2026, stating changes effective from 1 April 2026: online spends earn 5% up to a ₹2,000 maximum cashback per statement cycle, offline spends 1% with an overall ₹4,000 maximum per statement cycle. Cashback no longer applies on digital gaming platforms, tolls and government-related transactions, on top of existing exclusions. This is a real reduction from the earlier ₹5,000 online cap, confirmed in the bank’s own document. (The revision letter itself is dated 25 February 2026; SBI’s notices page carries 27 February 2026. Both dates appear because both appear on SBI’s own materials.)
Note how all four banks state their dates as effective from a quarter, not as on today. That distinction is the whole point. “Effective from 1st April 2026” means the terms can change again on any future date.
---
What each application costs your credit score
Every new credit card application is a hard enquiry, and it stays visible on your credit report for a period of years.
On the two-year figure specifically — it is a US bureau convention, not an Indian one, and the RBI citation an earlier draft hung on it does not support it. The part that matters is shorter than the citation: multiple card applications in a short window can read as credit hunger and affect your approval on the next card you want, including a mortgage. That is the reason to space them out.
Practical rules:
- Space applications 6 to 12 months apart. Not weeks.
- Apply for one card, use it for a full billing cycle, then consider the next.
- If you already have two cards earning well, a third is not worth an enquiry.
This is a real cost, and it never appears in a rewards calculator. Our credit score guide and CIBIL improvement tips cover what actually moves the number.
---
Your action step today
Pick one card and apply this week. Do not apply for two.
- If your spend is Amazon-heavy and you fly or play golf → Amazon Pay ICICI (₹0 fee, 5% on amazon.in) as card one. Add IndusInd Tiger months later only if you will genuinely use the lounges — its perks are fixed entitlements, so they cost nothing extra, but its rewards rate is poor at low spend.
- If food delivery and groceries are a genuine monthly line → HSBC Live+ (₹999, waived above ₹2L, 10% capped ₹1,200/month). Two checks before you count it. First, if your monthly food-and-grocery-and-utilities number is under ₹12,000, you are leaving part of the cap unused. Second, if your quarterly contactless fuel spend is under ₹10,000, you get nothing from the fuel perk.
Then write down three numbers on a sticky note — your monthly spend on that card, the earn rate, and the fee. Review it every quarter. That is the whole skill.
---
Sources
Every rate, cap and fee on this page comes from the bank’s own published document. The seven documents that carry the arithmetic:
1. ICICI Bank credit card MITC (PDF) — the 5%/3%/2%/1% rate table and the 11 October 2025 exclusions.
1. ICICI Amazon Pay credit card product page, Fees & Charges — the 3.75%/month and the 3.5–3.8% dynamic band.
1. IndusInd Bank Tiger credit card product page — the reward slab table, the ₹38,612 perk valuation at ₹82/USD, the fixed-entitlement clarification.
1. ICICI newsroom, 11 September 2025 — the separate Amazon Pay travel 5% route.
1. HSBC Live+ product page — the ₹1,200 cap, the 26 July 2026 structure, the ₹10,000/quarter fuel threshold.
1. SBI Card customer notices and HDFC Bank Infinia fees and charges — the 27 February 2026 notice effective 1 April 2026, and Infinia Metal ₹12,500.
---
Frequently asked questions
How much can a zero-fee credit card stack return per year?
At Rs 30,000 of monthly card spend, the Amazon Pay ICICI plus IndusInd Tiger pair returns Rs 8,784 a year in points and cash — up to Rs 39,396 if every lounge visit and golf game is used. A food-heavy pair returns about Rs 17,940.
Is a credit card stack better than a premium card with an annual fee?
At Rs 3,60,000 of annual spend, yes. The premium card's Rs 12,500 fee works out to 3.47% of that spend — it only wins once you already clear its waiver threshold, which in the example sits far above typical spending.
How many credit cards should I apply for?
Two for most people. Add a third only if it covers a category the first two miss, you can clear its fee waiver without shifting existing earn, and you pay every bill in full. Space applications 6-12 months apart because each is a hard enquiry.
What happens if I carry a balance on a rewards card?
Interest wipes out the rewards. Rates of 3.5-3.8% per month work out to roughly 42-45.6% a year, and credit-card interest rates are set by the bank's board — the RBI does not cap them.
Why did the SBI Cashback card's returns drop?
Per SBI Card's notice dated 27 February 2026 (effective 1 April 2026), online cashback is capped at Rs 2,000 per statement cycle, down from Rs 5,000, with 1% offline capped at an overall Rs 4,000 per cycle.
About the author
Om Patel is an investor, blogger and entrepreneur. Every guide is educational, not personalised advice; rates and rules are cited to official sources and reviewed with a visible date.
Educational content, not personalised advice. Rates change — verify on the bank's site before opening an account. How we make money