

Investment
SIP vs FD vs NPS Vatsalya: Where Should Your Money Go?
You have ₹10 lakh sitting idle. FD gives 7%. SIP says 12%. NPS Vatsalya says ₹1,000/month for your 5-year-old becomes ₹8.9 crore by 60. Everyone has an opinion. Your CA says FD. Your friend says...
You have ₹10 lakh sitting idle. FD gives 7%. SIP says 12%. NPS Vatsalya says ₹1,000/month for your 5-year-old becomes ₹8.9 crore by 60. Everyone has an opinion. Your CA says FD. Your friend says SIP. The bank RM pushes NPS Vatsalya for your kid. Let me show you the real numbers — inflation-adjusted, tax-adjusted, no marketing fluff. Plus a decision checklist so you know exactly where your next ₹10,000 goes this month. Three problems, one decision: 1. FD vs SIP — Banks show you 7%. They don't show you that at 30% tax bracket, post-tax is 4.9%. Inflation is 5.6%. You're losing purchasing power every year. 2. NPS Vatsalya — Sounds great: ₹1,000/month from age 5 to 60 = ₹8.9 crore. But the money is locked till 60. At 18, your kid can only withdraw 25% for education/medical. Is that what you want? 3. Too many options — PPF, SSY, MF SIP, NPS Vatsalya, FD. Each has different lock-ins, tax treatment, return profiles. Parents just want to know: where does the next ₹10K go?
### The FD Reality Check (Latest 2024-25 Rates)
| Bank | 1 Year | 3 Years | 5 Years |
| --- | --- | --- | --- |
| SBI | 6.75-6.80% | 6.75% | 6.50% |
| HDFC | 6.60% | 6.50-6.75% | 6.15-6.40% |
| ICICI | 6.70% | 6.90-7.00% | 6.50-7.00% |
| Post Office | 6.90% | 7.00% | 7.50% |
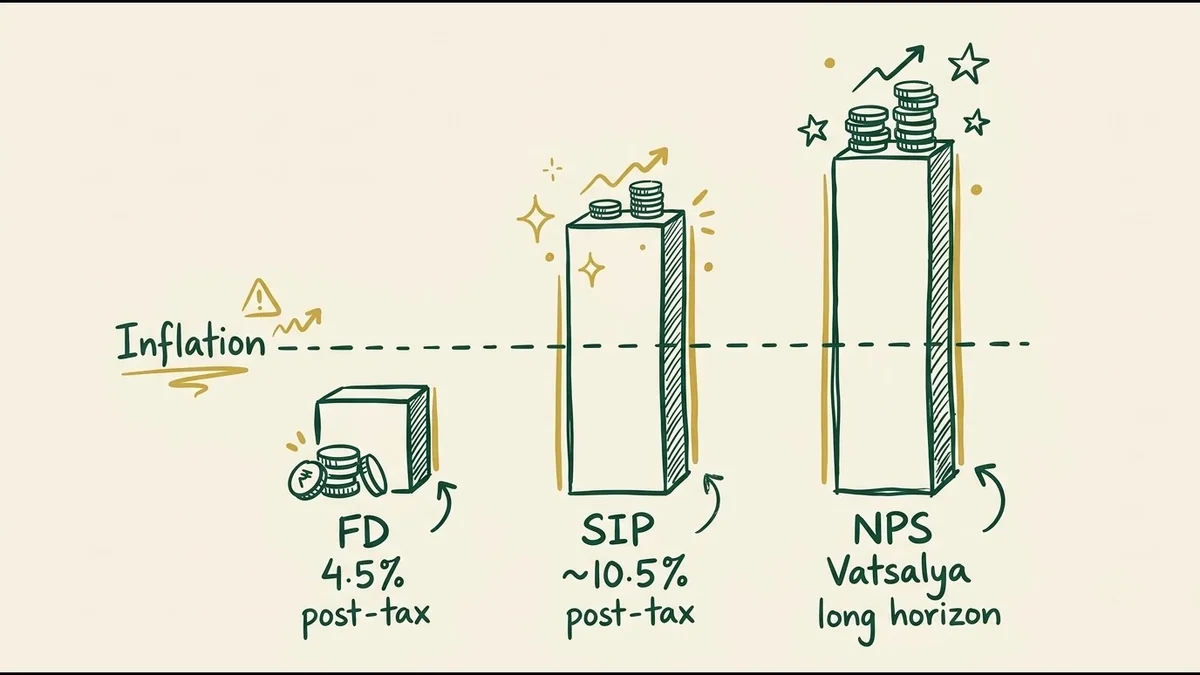
Senior citizens get +0.50%. Post Office offers the highest 5-year rate (7.50%) for all citizens. Post-tax at 30% slab: 7% → 4.9%. Post-tax + inflation (5.6%): -0.7% real return. Your ₹10L becomes worth ₹9.3L in purchasing power after 5 years.
### Mutual Fund Category Returns (Rolling Averages)
| Category | 5-Year CAGR | 10-Year CAGR | 15-Year CAGR |
| --- | --- | --- | --- |
| Large Cap | ~12-14% | ~11-13% | ~12-14% |
| Flexi Cap | ~13-15% | ~12-14% | ~13-15% |
| Mid Cap | ~17-20% | ~14-17% | ~16-18% |
| Small Cap | ~16-18% | ~15-17% | ~16-18% |
| Aggressive Hybrid | ~12-14% | ~10-12% | ~11-13% |
| Conservative Hybrid | ~7-9% | ~7-8% | ~8-9% |
| Corporate Bond | ~6-7% | ~6-7% | ~7-8% |
Returns are category averages for direct growth plans. Past performance ≠ future results. Post-tax (LTCG 12.5% above ₹1.25L): 12% → ~10.5% effective. Real return (Fisher eq): ~4.6%. Beats FD. But market risk is real.
### Inflation: The Silent Thief (CPI 2019-2025)
| FY | CPI Index | Inflation % |
| --- | --- | --- |
| 2019-20 | 146.3 | 4.8% |
| 2020-21 | 155.3 | 6.2% |
| 2021-22 | 164.0 | 5.5% |
| 2022-23 | 175.0 | 6.7% |
| 2023-24 | 184.0 | 5.6% |
| 2024-25 | 193.0 (prov) | ~4.9% |
| 6-Year Average | | ~5.6% |
Real Return = (1 + Nominal) / (1 + Inflation) - 1
| Asset | Nominal | Inflation | Real (Approx) | Real (Fisher) |
| --- | --- | --- | --- | --- |
| Equity MF (12%) | 12% | 5.6% | 6.4% | 6.06% |
| Aggressive Hybrid (11%) | 11% | 5.6% | 5.4% | 5.11% |
| Conservative Hybrid (8%) | 8% | 5.6% | 2.4% | 2.27% |
| Debt/Corp Bond (7%) | 7% | 5.6% | 1.4% | 1.33% |
| PPF (7.1%, Oct-Dec 2026) | 7.1% | 5.6% | 1.5% | 1.42% |
| SSY (8.2%, Oct-Dec 2026) | 8.2% | 5.6% | 2.6% | 2.46% |
| FD Post-Tax (4.5%) | 4.5% | 5.6% | -1.1% | -1.04% |
| NPS Vatsalya LC75 (12.5%) | 12.5% | 5.6% | 6.9% | 6.53% |
At 5.6% inflation, FDs and low-return debt instruments lose purchasing power.
---
FD is a losing game post-tax and inflation. At 30% bracket, 7% FD → 4.9% post-tax → -0.7% real. Your money shrinks. For long horizons (15+ years), equity wins. NPS Vatsalya LC75 at 12.5% → 6.5% real. ₹1,000/month for 55 years = ₹8.94 Cr. The "latte factor" compounding is real. But lock-in matters. NPS Vatsalya locks money till 60. PPF locks for 15 years. MF SIP gives full liquidity with LTCG tax drag. The layered approach works best: Max SSY/PPF for 80C + tax-free. Then NPS Vatsalya for retirement (no limit). Then MF SIP for flexibility. Do this today: Open SSY/PPF for your kid if not done. Start ₹1,000 NPS Vatsalya. Put the rest in MF SIP. Automate it.
---
Key takeaways
- A 7% FD nets 4.9% after 30% slab tax; against 5.6% average inflation that's about -0.7% real, so ₹10 lakh ends up worth ₹9.3 lakh in purchasing power after 5 years.
- Post Office FD pays the highest 5-year rate at 7.50%; SBI, HDFC and ICICI cluster between 6.15% and 7.00%.
- ₹1,000/month in NPS Vatsalya LC75 from age 5 compounds to about ₹8.94 crore by 60 at 12.5% — against ₹7.15 crore in an equity MF SIP at 12% and ₹1.1 crore in PPF.
- That Vatsalya corpus is locked till 60: before 18, only 25% can be withdrawn, and only for education or medical needs.
- Equity MF gains above ₹1.25 lakh a year attract 12.5% LTCG, turning a 12% return into roughly 10.5% effective — still more than double FD's post-tax 4.9%.
- NPS Vatsalya charges about 0.3-0.4% a year, lower than most mutual fund expense ratios of 0.5-1.5%.
- The layered order for a child's money: SSY or minor PPF first (80C plus EEE), NPS Vatsalya next (no annual cap), then MF SIP in the parent's name for flexibility.
NPS Vatsalya: The ₹1,000/Month Child Retirement Math
What Is It?
- Eligibility: All Indian citizens <18 years (including NRI/OCI)
- Account operated by: Guardian on behalf of minor
- Min contribution: ₹1,000 account opening + ₹1,000/year minimum
- Max contribution: No upper limit
- Asset allocation: Auto (LC75 = 75% equity, LC50 = 50% equity default, LC25 = 25% equity) or Active (E max 75%, C 100%, G 100%, A max 5%)
- Lock-in: Until age 60
- At 18: Fresh KYC mandatory within 3 months. Options: Continue Vatsalya, Shift to NPS Tier I, or Exit (100% lump sum if corpus ≤₹8L, else up to 80% lump sum, min 20% annuity)
Corpus Projections: ₹1,000/Month from Age 5 to 60 (55 Years)
7 of 7 rows
| Scheme | Assumed Return | Corpus at 18 (13 yrs) | Corpus at 60 (55 yrs) | Key Notes |
|---|---|---|---|---|
| NPS Vatsalya (LC75 / 75% Equity) | 12.5% | ~₹3.5L | ~₹8.94 Cr | Market-linked; 60% tax-free at 60, 40% annuity |
| NPS Vatsalya (LC50 / 50% Equity) | 10.5% | ~₹2.9L | ~₹4.3 Cr | Default auto choice |
| PPF | 7.1% (fixed, Oct-Dec 2026) | ~₹2.4L | ~₹81L | EEE tax; 15-yr lock-in, extendable in 5-yr blocks |
| SSY (Girl child only) | 8.2% (fixed, Oct-Dec 2026) | ~₹2.9L | N/A (matures at 21) | EEE tax; ₹1.5L/yr cap; only for girls <10 |
| MF SIP (Equity, 12% CAGR) | 12% | ~₹3.4L | ~₹7.15 Cr | LTCG 12.5% >₹1.25L/yr; full liquidity |
| MF SIP (Aggressive Hybrid, 11%) | 11% | ~₹3.1L | ~₹5.1 Cr | LTCG 12.5% >₹1.25L/yr; full liquidity |
| FD (6.5% post-tax ~4.5%) | 4.5% (post-tax) | ~₹2.0L | ~₹35-40L | Taxable at slab; no compounding advantage |
Assumes monthly ₹1,000, compounded monthly at each row's assumed rate, no step-up. NPS Vatsalya at 60: 60% lump sum tax-free, 40% annuity taxable. The PPF's own para 7(1)/(2) basis — monthly accrual on the minimum balance, credited once a year — gives about ₹75 lakh over the same 55 years.
Milestone Check: ₹1,000/Month at Different Ages
6 of 6 rows
| Age | Years Invested | NPS Vatsalya (12.5%) | MF SIP Equity (12%) | PPF (7.1%, Oct-Dec 2026) | SSY (8.2%, Oct-Dec 2026) |
|---|---|---|---|---|---|
| 18 | 13 | ₹3.5L | ₹3.4L | ₹2.4L | ₹2.9L |
| 21 | 16 | ₹5.2L | ₹5.0L | ₹3.2L | Matures: ₹4.9L |
| 30 | 25 | ₹14.5L | ₹13.8L | ₹6.8L | — |
| 40 | 35 | ₹45.2L | ₹42.1L | ₹13.2L | — |
| 50 | 45 | ₹1.28 Cr | ₹1.17 Cr | ₹23.4L | — |
| 60 | 55 | ₹8.94 Cr | ₹7.15 Cr | ₹1.1 Cr | — |
---
NPS Vatsalya vs PPF vs SSY vs MF SIP — Feature Comparison
10 of 10 rows
| Feature | NPS Vatsalya | PPF | SSY | MF SIP |
|---|---|---|---|---|
| Eligibility | Any child <18 (incl NRI/OCI) | Any child <18 | Girl child <10 only | Anyone |
| Annual Limit | No limit | ₹1.5L (family combined) | ₹1.5L | No limit |
| Minimum | ₹1,000/yr | ₹500/yr | ₹250/yr | ₹500/mo (varies) |
| Return Type | Market-linked (equity up to 75%) | Govt fixed (7.1%, Oct-Dec 2026) | Govt fixed (8.2%, Oct-Dec 2026) | Market-linked |
| Tax on Contribution | No 80C deduction | 80C up to ₹1.5L | 80C up to ₹1.5L | No 80C |
| Tax on Growth | Deferred | Tax-free | Tax-free | LTCG 12.5% >₹1.25L/yr |
| Tax on Exit | 60% tax-free, 40% annuity taxable | Fully tax-free (EEE) | Fully tax-free (EEE) | LTCG applicable |
| Lock-in | Until age 60 | 15 years (extendable) | Until girl turns 21 or marries | None |
| Partial Withdrawal | 25% after 3 yrs (education/medical) | From 7th year | 50% after 18 | Anytime |
| Best For | Retirement corpus | Medium-term tax-free lump sum | Girl child education/marriage | Wealth building + flexibility |
---
Decision Framework: Where to Put ₹1K/Month
6 of 6 rows
| Goal | Time Horizon | Risk Appetite | Recommended |
|---|---|---|---|
| Child retirement (age 60) | 50+ years | Moderate-High | NPS Vatsalya LC75 + MF SIP Equity |
| Child education (age 18) | 13-18 years | Low-Moderate | SSY (if girl) > PPF > MF Hybrid |
| Child marriage (age 21-25) | 16-20 years | Low-Moderate | SSY (if girl) > PPF > NPS Vatsalya (partial) |
| Wealth building + flexibility | 15-25 years | Moderate-High | MF SIP Flexi Cap + NPS Vatsalya |
| Conservative, guaranteed | Any | Very Low | PPF + SSY (if girl) |
| Tax saving + retirement | Long-term | Low | NPS Vatsalya (no 80C cap) + PPF |
Layered Strategy (Recommended)
1. First ₹1.5L/yr → SSY (girl) or PPF (boy) for 80C + EEE 2. Next ₹1.5L/yr (if parent PPF not maxed) → Minor PPF for additional tax-free compounding 3. Beyond that → NPS Vatsalya (no upper limit) for retirement 4. Education fund → MF SIP in parent's name (avoid clubbing) for flexibility
---
NPS Vatsalya: Step-by-Step Account Opening Guide
Where to Open (PoP - Points of Presence)
- Major banks: SBI, HDFC, ICICI, Axis, PNB, BoB, etc.
- India Post (post offices)
- Pension Funds directly: HDFC Pension, ICICI Prudential Pension, Kotak Pension, etc.
- Online: e-NPS portal (enps.nsdl.com / nps.kfintech.com)
Documents Required
- Birth certificate
- Aadhaar card (or enrollment slip)
- PAN (if available, else Form 60)
- PAN card
- Aadhaar card
- Address proof
- Bank account proof (cancelled cheque)
- Photograph
Process (Online via e-NPS)
1. Go to enps.nsdl.com → "National Pension System" → "Registration" 2. Select "NPS Vatsalya" → "New Registration" 3. Fill minor's details + guardian details 4. Upload documents 5. Choose PoP (bank/pension fund) 6. Select asset allocation (LC75 recommended for 0-18 age) 7. Make first contribution (min ₹1,000) 8. PRAN (Permanent Retirement Account Number) generated 9. PRAN card dispatched
Guardianship Transfer at 18
- Within 3 months of turning 18: Fresh KYC of child mandatory
- Child signs new registration form
- Child's own bank account linked
- Guardian's authority ceases
- Options: Continue Vatsalya, Shift to NPS Tier I, or Exit
---
Action Steps: Where to Put Next ₹10K This Month
If You're a Parent with a Child <10 (Girl)
1. ₹1,250/month → SSY (maxes ₹15K/yr, 8.2% for Oct-Dec 2026, guaranteed, EEE) 2. ₹1,000/month → NPS Vatsalya LC75 (retirement corpus, no limit) 3. Remaining → MF SIP Flexi Cap in your name (education fund, flexibility)
If You're a Parent with a Child <10 (Boy)
1. ₹1,250/month → PPF (minor account, 7.1% for Oct-Dec 2026, EEE, 80C) 2. ₹1,000/month → NPS Vatsalya LC75 3. Remaining → MF SIP Flexi Cap in your name
If You're a Professional (No Kids / Kids >18)
1. Emergency fund? → High-yield savings / Liquid fund (not FD) 2. 3-5 year goal? → Conservative Hybrid MF or Corporate Bond fund (better than FD post-tax) 3. 7+ years? → Flexi Cap / Large Cap MF SIP 4. Retirement + tax saving? → NPS Tier I (80CCD(1B) ₹50K over 80C) + MF SIP
Quick Decision Checklist
☐ Goal defined? (retirement / education / marriage / wealth) ☐ Time horizon known? ☐ Risk appetite assessed? (can you stomach -20% in a year?) ☐ Tax bracket considered? (FD post-tax vs MF LTCG) ☐ Liquidity needed? (NPS Vatsalya = locked till 60) ☐ 80C space available? (PPF/SSY first) ☐ Auto-choice selected? (LC75 for kids, LC50 default)
---
Risks & Limitations
- Market returns are not guaranteed — category averages ≠ fund returns; 15-year rolling returns have wide dispersion
- NPS Vatsalya lock-in is extreme — no access for education/emergencies; annuity taxation at 60 (40% must be annuitised)
- Inflation assumptions may change — 5.6% is 6-year average; future could be higher/lower
- Tax laws can change — LTCG, STCG, NPS taxation subject to Finance Act amendments
- Past performance ≠ future results — MF category returns are historical averages
- Clubbing provisions — MF SIP in minor's name may attract clubbing u/s 64(1A); use parent's name
- Charges eat returns — NPS Vatsalya total ~0.3-0.4% p.a. (lower than most MF expense ratios 0.5-1.5%)
- This is educational, not financial advice — consult a SEBI-registered investment advisor for your situation
Frequently asked questions
Is NPS Vatsalya better than a mutual fund SIP for my child?
For a pure retirement corpus, its 55-year runway and lower charges (0.3-0.4% versus 0.5-1.5%) win — ₹1,000 a month grows to about ₹8.94 crore at 12.5%, against ₹7.15 crore for the same money in an equity SIP. But the account locks till 60, with only a 25% pre-18 window for education or medical needs. A flexible education fund is better built in your own name.
Why does my FD lose money when the rate looks decent?
At the 30% tax slab, 7% becomes 4.9% after tax, and with average inflation near 5.6% the real return is about -0.7%. Purchasing power shrinks every year — ₹10 lakh ends up worth about ₹9.3 lakh after five years.
What happens to my child's Vatsalya account at 18?
The child must complete fresh KYC within 3 months of turning 18, and the guardian's authority ends. They can continue in Vatsalya till 21, shift to a regular NPS Tier I account, or exit — taking the full corpus if it's under ₹8 lakh, otherwise up to 80% as lump sum with at least 20% into an annuity.
How much do I need to open NPS Vatsalya?
₹1,000 to open the account and at least ₹1,000 a year after that. There's no upper limit, and grandparents or other relatives can contribute too.
I have no young kids — where should my money go instead?
Emergency fund first, then conservative hybrid or corporate bond funds for 3-5 year goals. For 7+ years, a flexi cap or large cap SIP beats FD after tax, and if you're on the old regime, NPS Tier I with ₹50,000 under 80CCD(1B) adds a deduction FD can't give.
About the author
Om Patel is an investor, blogger and entrepreneur. Every guide is educational, not personalised advice; rates and rules are cited to official sources and reviewed with a visible date.
Educational content, not personalised advice. Rates change — verify on the bank's site before opening an account. How we make money